The book you priced is not the book you are holding
Why re-scoring the in-force portfolio against the register is where the conversation starts.
Propalt Team · For insurance and risk teams
Every in-force book carries a gap between what was declared at inception and what the property actually is. Attributes were self-reported at quote, sometimes years ago, often never checked, and the errors do not cancel out. Floor areas run light, build ages sit in the wrong band, construction types get simplified. Individually these look small. Across a book they add up to exposure the pricing team has not seen, because nobody has compared the declared position to the record since the policy was written.
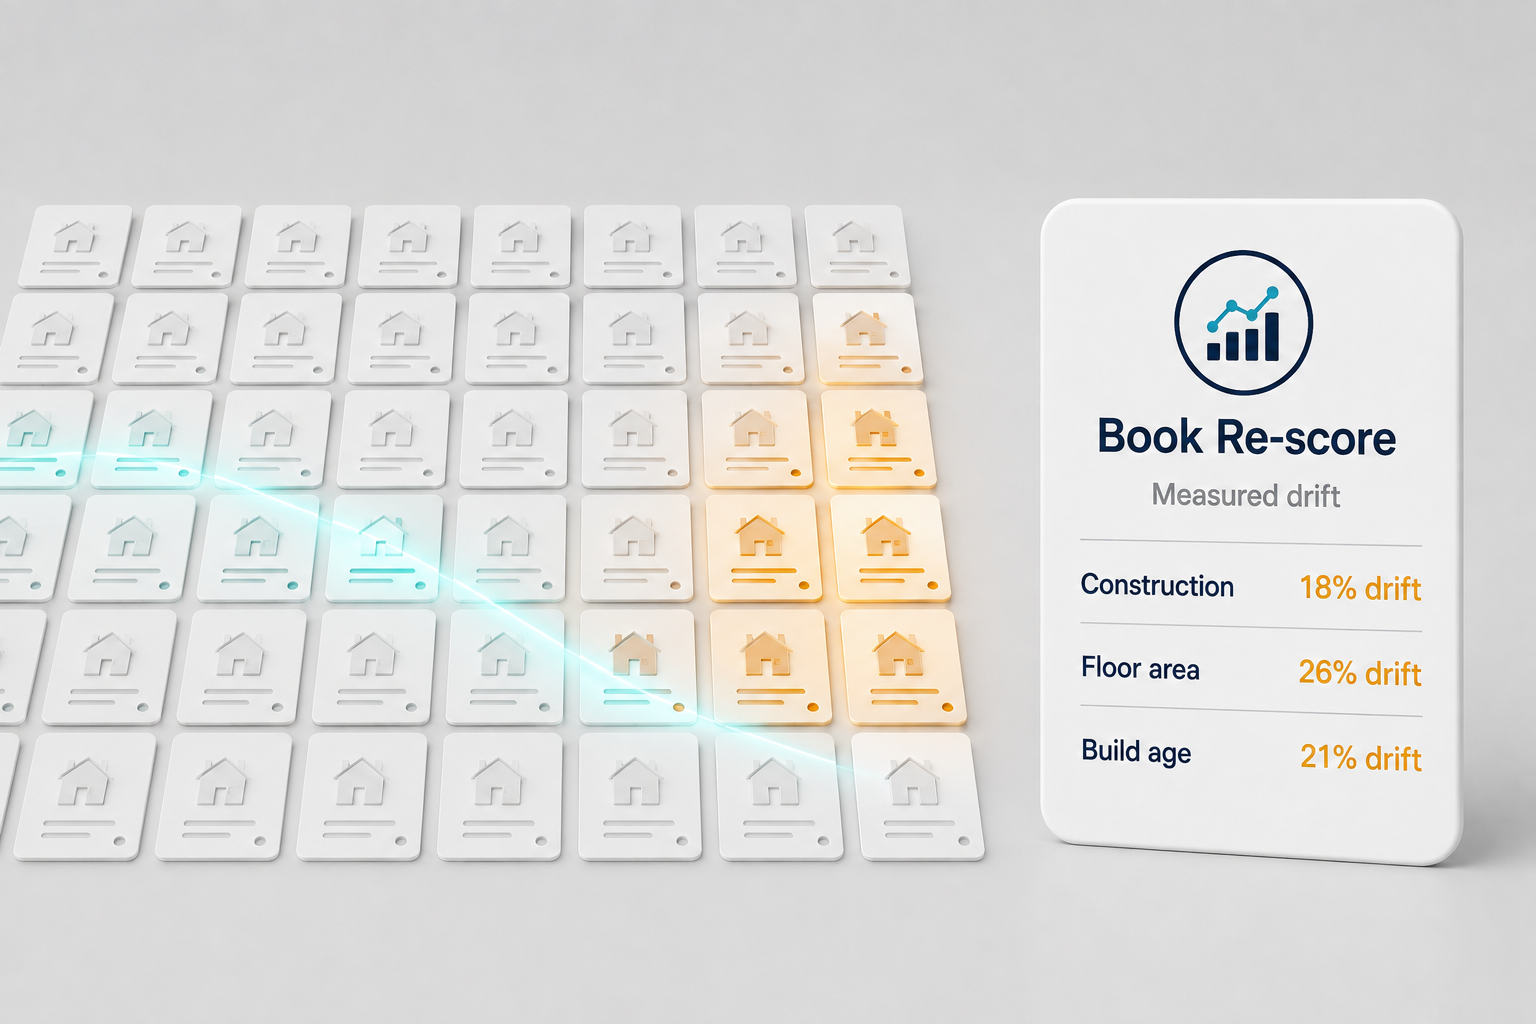
A book re-score closes that gap in one exercise. Run the in-force portfolio by UPRN, pull the verified attributes from HM Land Registry and the EPC register, and compare them line by line against what the policies say. The output is a measured drift: how far the book has moved from the record, segment by segment, expressed in the factors your pricing already runs on.
Why this is the exercise to run first
There is a reason this tends to be the first thing a pricing team does with verified data rather than the last. It requires no pricing change, no model rebuild and no customer contact to produce, yet it quantifies a problem that has been invisible. It turns an abstract worry about data quality into a number: the proportion of the book where the declared construction disagrees with the register, the share where floor area is understated, the aggregate rebuild-cost shortfall that implies.
| Segment (illustrative) | Self-reported | Register | Drift |
|---|---|---|---|
| Construction agrees | 100% | 82% | 18% |
| Floor area within 10% | 100% | 74% | 26% |
| Build-age band correct | 100% | 79% | 21% |
The figures are illustrative and every book differs, but the shape recurs: the declared position is treated as fully correct while the register shows meaningful disagreement. Once that drift is measured, the case for acting on it makes itself, which is why the re-score is so often the exercise that persuades.
From measurement to action, in order
A fair caution belongs here. A re-score measures drift; it does not by itself tell you the loss impact of correcting it, and not every discrepancy changes the price. Some attributes carry little rating signal, and a book can drift on a factor that barely moves loss. Measuring drift and quantifying its cost are two different steps, and it is worth keeping them separate.
The reframe is sequence. The re-score gives you the map: where the book has moved and by how much. From there you can prioritise, testing the segments with the largest drift against the factors known to carry signal, and decide where re-rating at renewal is worth the effort. It is the honest starting point precisely because it shows the size of the problem before anyone argues about the fix.
You cannot re-rate a book you have not measured against the record.
Measure the drift first, then decide what it costs to close it.
Try the Book re-score → · propalt.ai
Property and fabric attributes are drawn from HM Land Registry, the EPC register and the Propalt intelligence layer. Figures shown are illustrative. This article is general information for insurance professionals.
Book re-score
Runs the in-force book by UPRN and quantifies how far self-reported attributes have drifted from the register position, segment by segment.
🎯 Best used for
Measuring attribute drift across the in-force book
🔌 Propalt APIs used
search_properties get_property