A national shock is not what happens to your book
Why stress scenarios grounded in local evidence beat a single national haircut.
Propalt Team · For secured lenders
A stress test that applies one national house-price fall to every loan produces a clean number and an incomplete picture. Downturns are not evenly distributed. Some outcodes fall further and recover slower than the headline, others hold. A uniform national assumption applied across the book overstates the resilience of the fragile pockets and understates it elsewhere, and the single figure it produces hides both errors inside an average.
The concession is real: a national assumption is transparent, comparable and easy to govern, which is why regulators and boards understand it. But a national scenario and a locally grounded one are not mutually exclusive. You can run the prescribed national shock for comparability and also stress the book against how individual outcodes have actually behaved, so the headline number is accompanied by an understanding of where it would really bite.
History is the honest input
The most defensible way to stress a local market is against what it has actually done. An outcode's own price movement and transaction history through past cycles tells you how it tends to behave under pressure: how far it fell, how thin transactions became, how long stock took to sell. That is a better guide to its behaviour under stress than a national average that was assembled from markets nothing like it.
Applying a scenario against that local history rather than a flat assumption changes which loans surface. An outcode that has historically fallen harder and dried up faster than the national picture will show a deeper stressed LTV and a longer realisation period, exactly the combination that matters when you are modelling losses rather than just marks.
| Outcode (illustrative) | Base LTV | National-shock LTV | Local-evidence stressed LTV | Historic time to sold under stress |
|---|---|---|---|---|
| Outcode A | 68% | 79% | 77% | 55 days |
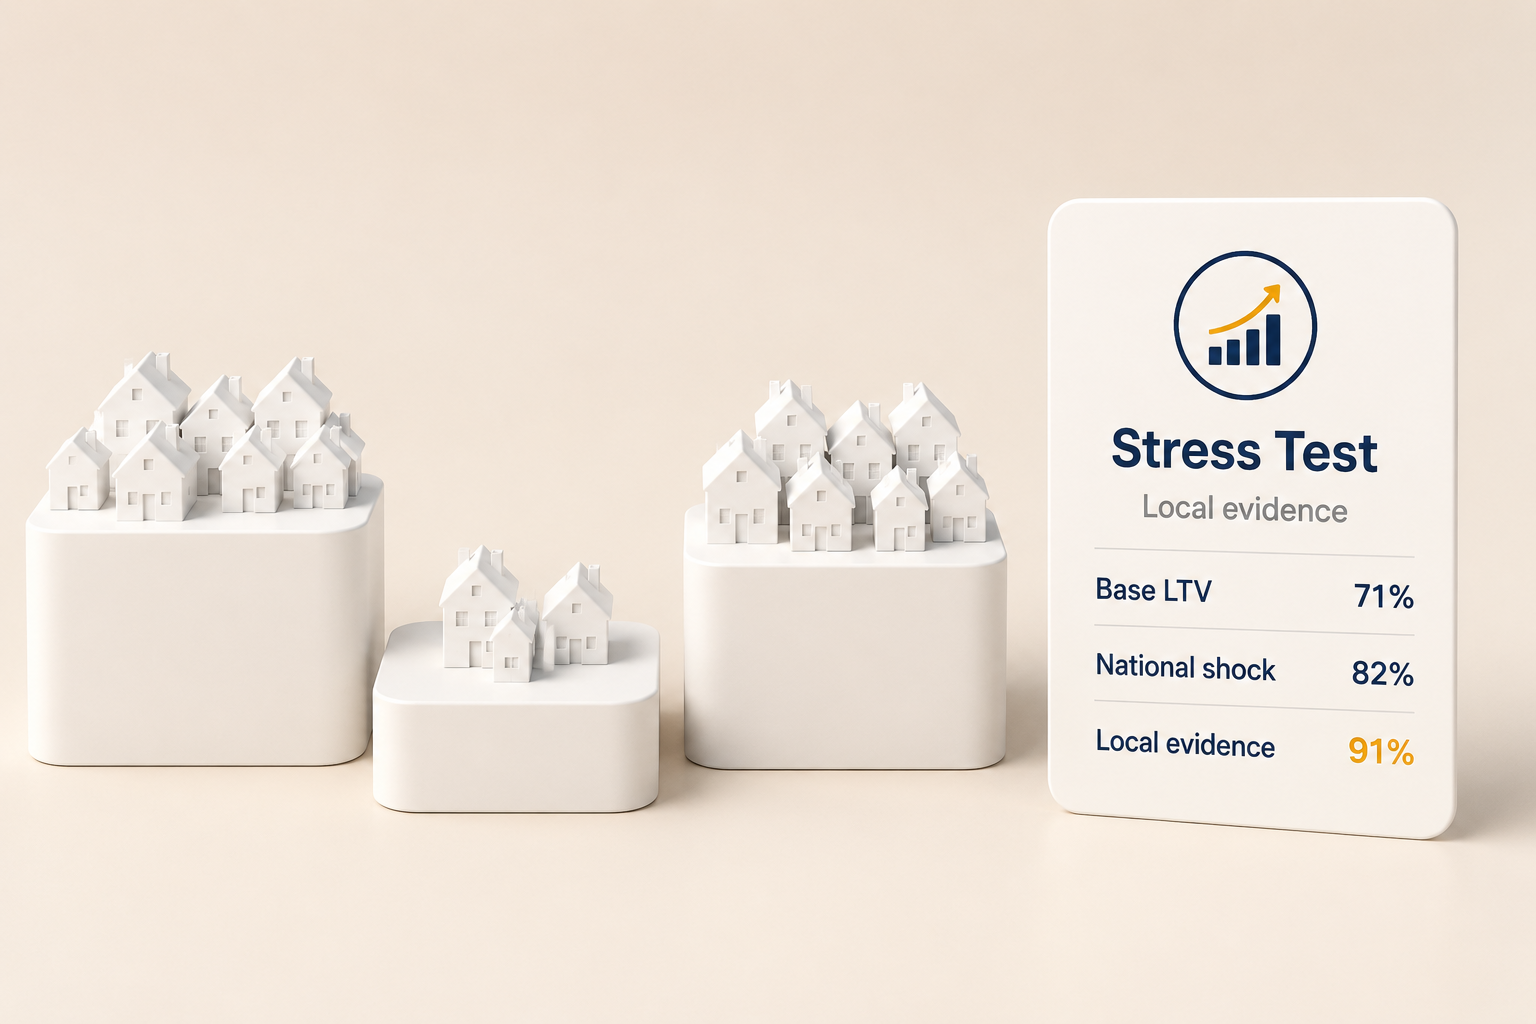
| Outcode B | 71% | 82% | 91% | 120 days |
| Outcode C | 66% | 77% | 75% | 60 days |
The table is illustrative. Outcode B is the row the national shock understates, on both stressed LTV and the time it would take to realise.
Where a uniform assumption breaks down
The weakness of a single national assumption is not that it is too harsh or too soft on average; it is that it is wrong in a different direction for different parts of the book, and the errors cancel in the total. That cancellation is comforting and misleading. The outcodes that would actually drive losses in a downturn are precisely the ones a national average smooths over, because their behaviour departs most from the mean.
For a risk function under PRA stress-testing expectations, grounding scenarios in local evidence strengthens the story you can tell. You can show not just a stressed capital number but where in the book the stress concentrates, supported by how those markets have behaved before, with transaction history behind the realisation assumptions. A board challenging the result can be shown the local evidence rather than asked to trust a single national factor, which is a more honest place to argue from.
A national haircut is right about the average and wrong about the outcodes that would actually hurt you.
Stress the book you have, not the average of every book.
Try the Local-evidence stress test → · propalt.ai
Price and transaction data is drawn from HM Land Registry and the Propalt intelligence layer. Figures shown are illustrative. This article is general information for lending risk professionals.
Local-evidence stress test
Applies stress scenarios against actual outcode-level price movement and transaction history rather than a single national assumption, showing where the stress really concentrates.
🎯 Best used for
Locally grounded book stress testing
🔌 Propalt APIs used
get_hpi get_market_analysis get_property_history