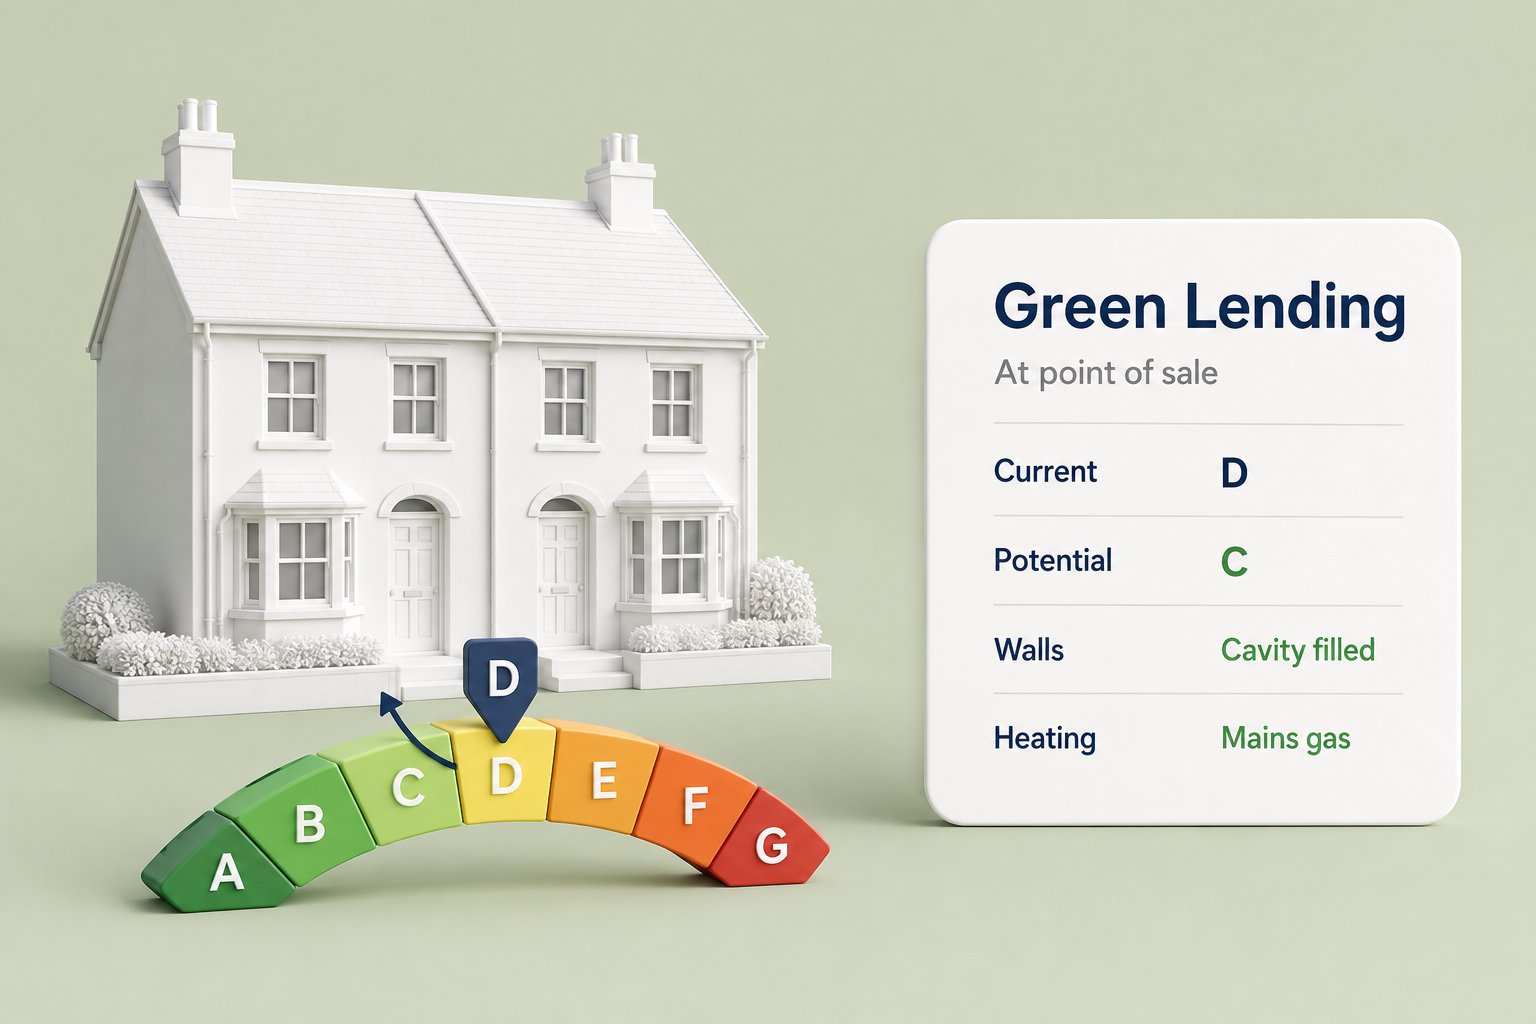
The green rate the client qualified for, found after they had already fixed
Current and potential EPC rating, wall and roof construction, heating system and fuel, read at the point of sale rather than after the survey.
Propalt Team · For mortgage brokers
Green mortgage ranges have grown from a novelty into a real pricing lever, and most of them hang on one thing: the EPC rating. A property already at band C, or one that can reach it, may open a lower rate, a higher loan-to-value, or a cashback on retrofit works. The problem is timing. If the first time anyone looks at the EPC is when the valuation lands, the client has usually already been steered toward a standard product, and the green option becomes a missed line rather than a recommendation.
You do not need the survey to know where the property stands. The EPC register already holds the current rating, the potential rating and the fabric detail behind both. Reading it at the point of sale turns green lending from an afterthought into a criterion you can match against from the start.
Current rating is the gate, potential rating is the conversation
The current rating tells you which products the property qualifies for today. The potential rating tells you what a few sensible works could earn, which matters for ranges that reward improvement or lend against a target band. Between them sits the fabric: wall and roof construction, and the heating system and its fuel. Solid walls, an old boiler or electric storage heating change both the retrofit cost and the realistic path to a better band.
| Property (illustrative) | Current EPC | Potential EPC | Walls | Heating | Green fit |
|---|---|---|---|---|---|
| A | C | B | Cavity, filled | Mains gas boiler | Qualifies now |
| B | D | C | Cavity, filled | Mains gas boiler | Reachable, discuss works |
| C | E | D | Solid | Electric storage | Harder, set expectations |
The table is illustrative. The point is that fabric decides whether the potential rating is a short conversation or a major project, and the client deserves that read before they commit to a product.
Match the client, do not just quote the property
A green product is a good outcome only when it genuinely suits the case. Reading the fabric early lets you separate the property that qualifies today, the one a modest improvement brings into range, and the one where the retrofit cost outweighs the rate benefit. That is a more honest recommendation than pushing every EPC C toward a green badge. It also gives the client something concrete to act on: the specific works that move the rating, not a vague nudge to be greener.
The rate a property qualifies for is set by data that already exists, long before the surveyor visits.
Read the EPC and the fabric while the recommendation is still open.
Try the Green mortgage matcher → · propalt.ai
EPC and fabric data is drawn from the EPC register and the Propalt intelligence layer. Figures shown are illustrative. This article is general information for mortgage professionals.
Green mortgage matcher
Returns current and potential EPC ratings alongside wall and roof construction and heating system and fuel, so a client can be matched to green product criteria at the point of sale rather than after the survey.
🎯 Best used for
Matching clients to green mortgage criteria early
🔌 Propalt APIs used
get_epc_fabric_by_property_id get_epc_fabric_by_postcode